

Build & Fix Credit - Dovly AI
by Dovly.com
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
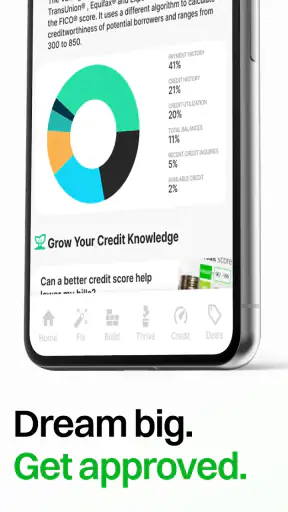
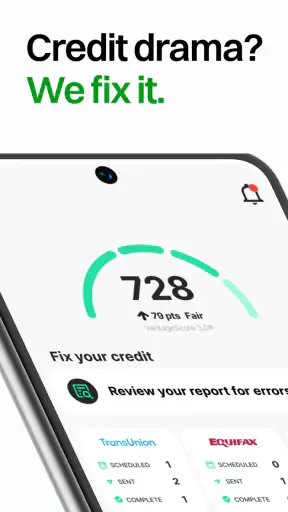
 Analysis by Getfullapps
When I look at a finance app, I want to know what it can actually do for me on an ordinary week, not just what its store blurb promises. Build & Fix Credit - Dovly AI is aimed at people who are trying to improve their credit position and need a more organized starting point. I found its central idea easy to understand: bring your credit-building work into one place, use the app’s AI-led guidance, and keep an eye on the actions that may help you move forward.
That focus makes it different from a general budgeting app. It is not primarily about tracking groceries, splitting bills, or building a complete household spending plan. It is a credit-focused tool from Dovly.com, and the experience makes most sense when your immediate goal is understanding and improving your credit rather than managing every part of your finances.
My overall view is that Dovly AI works best as a structured companion for a credit-improvement routine, not as a magic repair button. It can help turn a vague concern into a sequence of tasks and checks, but you still need patience, accurate personal information, and a willingness to review what the app is asking you to do.
Starting with a credit problem instead of a blank budget
The most realistic way to approach this app is to begin with a specific situation. Perhaps you have been rejected for a card, you are preparing to rent a home, or you simply know your credit history needs attention but do not know which step deserves priority. In that state, a broad personal-finance app can feel distracting because it gives you charts and categories without necessarily telling you what to do next.
Dovly AI is more focused. Its store summary presents it as an AI credit builder, and that emphasis carries through the way I think about using it: start with your credit journey, then use the app to create a clearer path. The useful change is not that the app removes responsibility. It gives the responsibility a place to live, so you are less likely to forget what you checked, what you need to follow up on, or which part of your credit situation deserves attention first.
The app is free to install, with optional in-app purchases ranging from $0.99 to $199.99 per item. That makes the first decision relatively simple: you can explore the basic experience before deciding whether any paid option fits your situation. I would still read each purchase screen carefully. A free download does not automatically mean every useful part of the service is free, and credit-related products deserve more price awareness than casual entertainment apps.
It is suitable for Everyone, and the minimum operating-system requirement is Android 7.0. On iOS, the practical question is less about the label and more about whether your device supports the current app experience. The current version is 9.4.0, so I would keep the app updated if you decide to rely on it for an ongoing routine.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What I would prepare before opening it
I would not begin by tapping through screens without a goal. First, I would write down why I want help: missed payments, limited credit history, uncertainty about what appears on my records, or a general need to become more organized. That small preparation matters because AI guidance is easier to judge when you can compare it with a real concern.
I would also make sure I can review personal financial information calmly. Credit work is sensitive, and rushing through identity or account-related steps is a bad idea. I would check names, dates, account details, and any requested connections before continuing. If something looks unfamiliar, I would pause instead of assuming the app must be right.
This is one of the first trade-offs. A focused credit app can save time compared with researching every step yourself, but it also concentrates attention on information that needs careful handling. Convenience is valuable only when it does not replace basic checking.
Following the workflow from setup to action
I use this section to connect the first setup choices with the point where the app’s guidance becomes a real-world task. The useful test is not how quickly I can move through screens, but whether I finish with one clear next step and know what still needs checking outside the app. That distinction makes the workflow easier to judge before relying on it week after week.
Step one: define the purpose
The first useful handoff is from your concern to the app’s guidance. You bring the situation; Dovly AI helps organize it into a credit-oriented workflow. I like this approach because “fix my credit” is too broad to act on. A practical tool needs to turn that phrase into smaller decisions, such as what to review, what to monitor, and what should happen next.
This is also where expectations need to be realistic. An app cannot change the underlying facts of your financial history merely because you opened it. It may help you identify work, but the outcome still depends on correct records, responsible payments, time, and the decisions you make outside the app. Anyone promising an instant transformation should be treated cautiously, no matter how polished the interface looks.
Step two: move through the guided experience
The AI element is most useful when it reduces the amount of searching you have to do. Instead of opening several websites and trying to decide which advice applies to you, you can use the app as a central place for credit-building direction. In my experience, that kind of guided sequence is especially helpful for beginners who understand that credit matters but do not yet have a reliable process.
I would treat each recommendation as a prompt to investigate, not as an instruction to follow blindly. For example, if the app points me toward a particular area of my credit life, I would ask what information supports that suggestion, what action is actually required, and whether the proposed step has a cost or a longer-term consequence. This habit protects you from confusing a convenient recommendation with a guaranteed result.
A useful personal workflow is to review the app at a fixed time each week, record the action you completed, and note anything that needs outside follow-up. That turns the app from a one-time curiosity into a routine. The non-obvious benefit is behavioral: a visible sequence can make it easier to continue when credit improvement feels slow and abstract.
Step three: separate app tasks from real-world tasks
This separation is essential. Some work happens inside the app, such as reviewing guidance or checking your progress. Other work may involve your bank, a lender, a creditor, or your own payment calendar. The app can help you remember the handoff, but it cannot personally complete every responsibility that affects your credit life.
I would keep a simple note beside the app with three columns: what Dovly AI suggested, what I did, and what still needs confirmation elsewhere. This is more than an organizational trick. It prevents a common mistake in finance apps: assuming that seeing a task marked or discussed means the outside institution has already processed it.
That distinction also answers a question many new users have: can the app replace contacting a creditor or checking an official source? I would not use it that way. It can be a useful guide and central workspace, but important account details should still be checked through the relevant financial institution or official record when the decision carries serious consequences.
Step four: review before paying for anything
Because the app includes in-app purchases, I would make payment decisions only after understanding what the specific option offers and whether it addresses my actual need. The listed range runs from $0.99 to $199.99 per item, which is a wide spread. That alone is a reason to avoid tapping quickly through an upgrade screen.
My rule would be simple: if I cannot explain what a purchase changes in my workflow, I would not buy it yet. I would first use the free experience long enough to decide whether the guidance is clear, whether I return to the app consistently, and whether it helps me take sensible action. Credit improvement is a long-term subject, so an expensive option should earn its place through clear usefulness rather than urgency.
Step five: keep the routine alive
The outcome of a credit-building app depends heavily on follow-through. I would use reminders from my own calendar alongside the app, especially for payment dates and documents that need review. This is a practical limitation of relying on any single finance tool: even a well-organized app cannot make a missed deadline harmless.
I would also avoid checking progress obsessively. Credit changes are not always immediate, and constant checking can create anxiety without improving the underlying situation. A scheduled review gives me enough distance to judge whether I am actually completing useful steps instead of simply opening the app often.
Where the handoffs feel helpful and where they become awkward
The strongest handoff is between confusion and structure. If I do not know where to begin, an AI-guided credit builder can give me a more approachable entry point than a collection of disconnected articles. The app’s narrow purpose is an advantage here: it does not ask me to build a complete financial dashboard before addressing the credit question that brought me in.
The next handoff, from guidance to outside action, is more demanding. This is where the app becomes a companion rather than a complete solution. I still have to understand what a recommendation means, decide whether it fits my circumstances, and complete any necessary work with the appropriate institution. Users who expect a single tap to resolve a complicated credit issue may find the experience disappointing.
Another friction point is the possibility of information overload. Credit terminology can be intimidating, and even friendly guidance may leave a beginner with follow-up questions. I would slow down whenever a suggestion involves borrowing, opening an account, paying a fee, or making a claim about a record. A clean workflow is helpful, but it should not encourage rushed financial decisions.
Privacy is part of the handoff too. Any finance app asks you to think carefully about what you are sharing and why. I would read the relevant permission and account-connection screens, use a strong device lock, and avoid using the app on an unsecured public device. These are not reasons to dismiss Dovly AI specifically; they are sensible habits whenever personal credit information is involved.
The app’s popularity suggests that many people find the concept approachable. It has passed 1 million installs, carries a 4.7 average from around 83 thousand ratings, and has about 5.6 thousand written reviews. Those figures make it easier to see why a newcomer might try it, but they do not remove the need to judge whether its workflow suits your own situation. A high average rating can reflect ease of use while saying less about how well the app fits a complex or unusual credit problem.
What the result looks like in everyday life
Imagine I am preparing to apply for an apartment. I know my credit history could affect the application, but I do not want to spend an evening jumping between general budgeting tools, search results, and scattered notes. I would open Dovly AI, use its credit-focused guidance to establish what deserves attention, and then write down the tasks that belong outside the app.
After that first session, I might use a weekly check-in to confirm that I completed the practical work I could control. I would keep copies of relevant correspondence, note dates, and avoid assuming that a recommendation itself changes my record. Before applying, I would review my overall position through appropriate official channels and make sure the application timing makes sense.
In that scenario, the app’s value is not a dramatic before-and-after moment. It is the reduction of scattered effort. I have a place to begin, a way to think about next steps, and a routine that makes me less likely to ignore the issue. For someone who feels stuck because the process seems complicated, that can be a meaningful result.
It is also important to define what success should mean. I would measure success by better understanding, consistent follow-through, and fewer forgotten tasks before expecting a visible credit change. That mindset prevents disappointment and makes it easier to identify whether the app is genuinely helping after several review sessions.
Who will get the most from it
I think this app is a good fit for a beginner who wants credit-specific direction without building a system from scratch. It can also help someone who has tried to improve their credit but keeps losing track of what to review next. The AI framing may feel less intimidating than reading long explanations and deciding alone which parts apply.
It may suit a person who wants a focused tool alongside a bank app or a budgeting app. Those tools serve different purposes: a bank app shows transactions and balances, while a budget app helps plan spending. Dovly AI belongs in the credit-improvement lane, so using it beside—not instead of—those tools makes more sense.
I would be more cautious if you already have a detailed credit-management system, understand the relevant terminology, and prefer to handle every decision directly through official sources. In that case, the app may add another layer rather than save time. It is also not the right choice for someone looking for investment analysis, debt payoff modeling, tax preparation, or a complete household budget.
People in urgent financial trouble should not treat it as a substitute for qualified advice. If a decision involves legal action, serious debt, identity theft, or a dispute with major consequences, I would seek appropriate professional or official help and use the app only as an organizing aid.
Where the flow breaks down
The biggest break occurs when a user confuses guidance with guaranteed repair. Credit is affected by real financial behavior and by information held across institutions. A well-designed workflow can help you act more consistently, but it cannot promise that every issue will disappear or that every recommendation will produce the same result for every person.
The second break is cost awareness. Since optional purchases can reach $199.99 per item, I would never judge value from the download price alone. Someone who only needs basic education and a simple routine may be satisfied without paying. Someone considering a purchase should compare the specific benefit with free official resources and with the value of simply maintaining reliable payment habits.
The third break is incomplete follow-through. If I open the app once, read several suggestions, and then ignore the outside tasks, the workflow stops at the most comfortable stage. The app can make the beginning easier, but it cannot supply discipline. My practical fix would be to choose one manageable action at a time and record its completion rather than collecting advice endlessly.
Finally, the AI approach may not feel personal enough for every situation. Guidance can organize common needs, but unusual credit histories, conflicting records, or complicated debt circumstances may require human interpretation. I would use the app to prepare better questions, not to avoid asking them when the situation goes beyond routine credit-building.
My recommendation after using the full workflow
Build & Fix Credit - Dovly AI is worth considering if you want a clear, credit-centered starting point and prefer guided steps to searching for answers on your own. I appreciate that its purpose is narrower than a general finance app, because that makes it easier to build a routine around one important goal. The free entry point also gives cautious users room to understand the experience before considering optional purchases.
I would recommend approaching it with a notebook, a calendar, and realistic expectations. Use the app to organize your questions and actions, verify important information through the appropriate outside source, and judge progress by consistency before looking for fast results. That combination makes the workflow more dependable than relying on the app alone.
For a newcomer, the focused guidance can be genuinely useful. For an experienced credit manager, it may be unnecessary. For anyone expecting instant repair or a replacement for professional help, it is the wrong tool. My final opinion is positive but measured: Dovly AI is most valuable when it turns credit improvement into a repeatable personal process, while leaving the final decisions and real-world follow-through in your hands.
Pros
- AI-guided credit improvement plan is easy for beginners to follow.
- Automated dispute assistance can save time on credit-report issues.
- Progress tracking makes changes to your credit profile easier to monitor.
- Personalized recommendations help prioritize potentially useful actions.
- Simple interface keeps credit-management tasks organized in one place.
Cons
- Some features require a paid subscription after the trial period.
- Results depend on accurate data from participating credit bureaus.
- Credit improvement is not immediate and may take several billing cycles.
- Dispute outcomes are not guaranteed and depend on creditor responses.
- Availability and features may vary by location and credit-report provider.
FAQs for Build & Fix Credit - Dovly AI
What is Build & Fix Credit - Dovly AI?
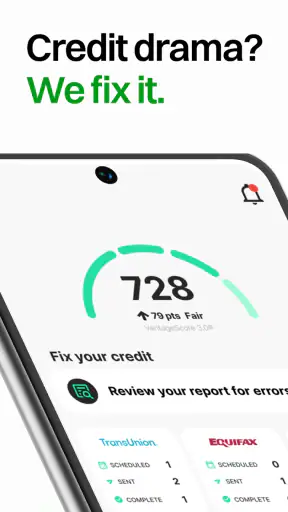
Build & Fix Credit - Dovly AI is a credit-management app designed to help users monitor and improve their credit profile. It combines credit tracking, personalized recommendations, dispute-related tools, and educational guidance in one mobile experience. The app is intended to make credit improvement easier to understand, although results depend on your individual credit history and the actions you take.
How does Dovly AI help improve my credit score?
The app reviews information connected to your credit profile and may identify areas that could be affecting your score, such as late payments, high balances, or inaccurate entries. It can then provide suggestions and tools for addressing potential issues. However, Dovly cannot guarantee a specific score increase, because credit bureaus, lenders, payment behavior, account age, and other personal factors determine how quickly your score changes.
Is Build & Fix Credit - Dovly AI free to use?
Dovly may offer access to some basic features at no cost, while more advanced credit-improvement services can require a paid plan or subscription. Before downloading or starting a trial, carefully review the current pricing, renewal terms, and cancellation policy shown in the app store or during registration. A free trial may automatically convert into a paid subscription if it is not canceled on time.
Is my personal and financial information safe in the app?
Because credit-management services may require sensitive information, including identity details and access to credit-related data, users should review Dovly’s privacy policy and security information before creating an account. Use only the official Android or iOS download source, choose a strong unique password, and avoid sharing verification codes. No app can eliminate every online risk, so monitor your accounts regularly.
Can Dovly remove negative information from my credit report?
Dovly may help you identify information that appears inaccurate, incomplete, or potentially disputable, and it can provide tools or guidance for addressing those entries. It cannot legally remove accurate negative information simply because it lowers your score. Credit-report corrections depend on the investigation and response of the relevant credit bureau or data furnisher, so outcomes and timelines can vary significantly.

Build & Fix Credit - Dovly AI
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@dovly.com, visit https://www.dovly.com, or review their https://www.dovly.com/privacy-policy.










